Global Chemical Industry Outlook 2026: Ethylene, Hydrogen, CapEx
Video Language
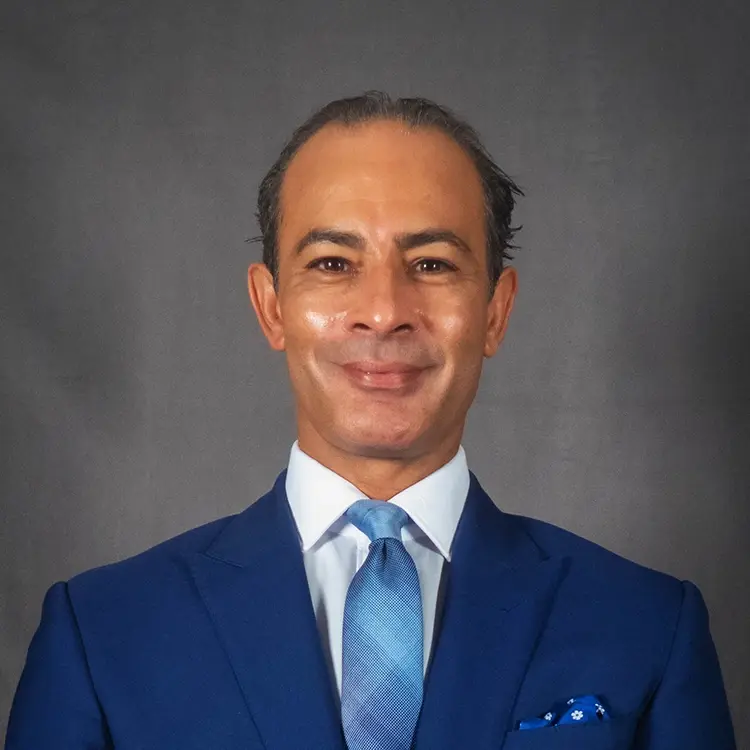
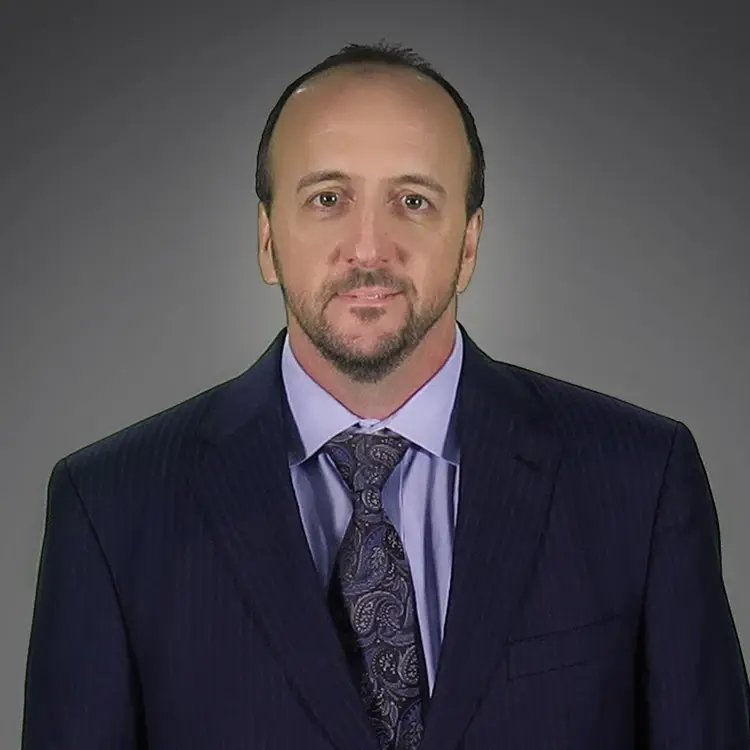
Why are chemical projects shifting rather than disappearing? In this episode of Navigating the Currents of Change, Trey Hamblet (IIR’s Senior Vice President of Chemical Processing Research) joins Shaheen Chohan to unpack where global chemical spending is heading, from a project pipeline just short of $1 trillion at the start of 2026 to as much as 17% of global ethylene capacity offline at once.
Together they cover how geopolitical disruption to naphtha trade flows reshaped operating rates, why green and blue commodities are decoupling across the US, Europe, and Asia, and what the shift from grassroots plants toward expansions means for US spending. They also explore China’s ethylene and green hydrogen plans, North America’s feedstock cost advantage, and the 2027 maintenance outlook.
The outlook: cautious optimism, with spending shifting toward higher-value specialty chemicals.
Together they cover how geopolitical disruption to naphtha trade flows reshaped operating rates, why green and blue commodities are decoupling across the US, Europe, and Asia, and what the shift from grassroots plants toward expansions means for US spending. They also explore China’s ethylene and green hydrogen plans, North America’s feedstock cost advantage, and the 2027 maintenance outlook.
The outlook: cautious optimism, with spending shifting toward higher-value specialty chemicals.
Shaheen Chohan (00:00):
Global chemical production growth has softened over much of the course of this year, some of which is due to still moderate only economic activity and softer demand across some of those key end-use markets. And all of this is coming at a time when overcapacity remains a core problem right now. So the big questions remain: how will capital spending play out over the course of this year and into next off rising feedstock costs for many producers? And will the green and blue commodities that have been a growth engine for the last year continue, or will they falter?
Welcome to Navigating the Currents of Change, where we bring together over four decades of trusted research, data, and industry insights, built for the Answer Age. Let's dive in. My name is Shaheen Chohan, and I lead Global Analytics here at Industrial Info Resources.
And to help me unpick some of the trends and put some answers to those questions, I am delighted to be joined by Trey Hamblet, who is IIR's Senior Vice President of Chemical Processing Research. Welcome, Trey.
Trey Hamblet (01:26):
Thanks for having me.
Shaheen Chohan (01:26):
Now, Trey, your industry obviously aligns very closely to the ebbs and flows of the broader economic performance. Has the chemical industry and the levels of spending that we've seen in previous years, is it still moving at pace and proceeding? Certainly of the first half of this year, or have we seen some erosion of that planned spending?
Trey Hamblet (01:46):
So we've seen a little bit of both. You know, in some respects, when we look at where the spend levels were in 2025 at the same time, and we're kind of on par, we're kind of keeping pace.
We've had an anomaly, I'll call it, really, for the last five plus years in this huge accumulation of projects and pent-up spending we've started each year with. We reached a new historical high when we got to the beginning of 2026. We had just short of $1 trillion globally across the chemical industry that had some potential to start construction this year.
As always happens, we see those plans move. Roughly 85% of that fallout stayed and in some phase of active planning. So that's a good thing. Meaning that there's expectations and optimism that we're going to continue to see those projects move. Much of it moved into 27. Some of it moved out as far as 2030 or 2031.
So we started the year somewhat in a similar fashion than we have in the past, and that we were seeing this accumulation of projects continue to move forward. We've seen a slight uptick in cancellations in some regions more than others.
You may have mentioned in your question about blue and green, and certainly here in the domestic market where I reside in the US, we've seen an increase in the cancellation of green hydrogen, blue, you know, carbon capture projects, etc., but that's kind of where we start for the year.
Shaheen Chohan (03:23):
Now, gone are the days of the multiple big ethylene capacity waves that we've seen over the last decade in the US. What we are seeing is most of the new capacity that is being built, and certainly still being proposed, seems to be in Asia and more specifically in China. Why is that?
Trey Hamblet (03:41):
Well, you know, Asia is the epicenter of demand, right? We hear about population growth. It's one of the key components that drives chemical industry spending is population growth. Because with population growth you have more plastics. You have more paints, coatings, automobiles. Everything that we consume has a plastic or chemical component to it, right? And Asia is one of those biggest growth markets.
What's interesting talking about China specifically is China produces a great deal of ethylene, one of the father chemicals of the chemical industry, if you will, because it's, you know, the starting point for some of the other commodities in the industry.
There's some 60 plus billion dollars worth of future, you know, years not this year, not next year, but future years worth of investments for ethylene alone.
What's interesting is we've got 60 plus billion in green hydrogen in China as well. And that's a relatively new phenomenon. And green hydrogen probably makes more sense in some respects for that region than others, because there's some 8000 renewable power projects planned across China, right? So their access to that renewable power, even if we only saw a fraction of that come to fruition, you know, would be very supportive of that green hydrogen.
So you've got traditional investments, ethylene, you've got the newer green hydrogen, which might turn into green ammonia and other commodities. So China is going to continue to be that, you know, epicenter of growth going forward as it has played that leading role in the last decade or more.
Shaheen Chohan (05:13):
Looking at the macro picture, chemicals haven't so far been on the radar for US tariffs so far. But obviously geopolitics does play a more, I guess, indirect role in influencing some of those chemical project investments and the considerations and decisions, just simply by the very global nature of production and also trade flow. Have you seen any major disruptions to the sort of balance between supply and demand, and how has that shifted the location or indeed the type of projects that are still being proposed?
Trey Hamblet (05:57):
Yes. So we've seen the geopolitical and other, you know, conflicts we've experienced this year have a significant impact on trade flows. You mentioned trade flows in your question. And when we used our Energy Capacity Insights tool, where we look at future capacities, we look at operational base of capacities, future offline events, etc., we saw a significant drop in operating rates specifically for ethylene. Again, one of those commodities that's, you know, a starting point for so much else in the industry.
When the year started, we had on average, a four, maybe 5% offline capacity globally for ethylene when you rolled into March and April, when we got into our deepest trenches of the geopolitical escalations this year, we saw as much as 17% of that capacity offline globally, which is tremendous. That's an equivalent of, I think, 66 or so billion pounds equivalent of ethylene capacity offline at once.
It wasn't just in the Middle East, and it wasn't just in the Russia-Ukraine environment. This was in Japan, Korea, China. When the trade flows for naphtha, which is a key feedstock for ethylene in those Asian and European regions, stopped or got disrupted, it had a significant impact on operating rates and trade flows.
And of course, this is influencing decisions on future maintenance plants because we don't know yet for some of these producers in China, Japan or Korea, just using some easy examples that had unplanned time for 30 days, 60 days going on 90 days in some cases of derails or completely offline, we don't know yet. Did they take an optimistic view and perform some maintenance that had been originally planned for 27 or 28? And so now that turnarounds move forward, or did they use that to say, okay, we're going to take that window and go even longer before the next turnaround because we didn't run during this period? So that's going to have an impact on maintenance decisions and we'll start to reveal that or interpret what that means to the market over the coming months.
But it also puts stress on decisions for capital projects. Right? The indecision and operating rates and storage volumes and trade flows makes it really difficult to make a decision on some of your really large CapEx projects that are benchmarks in the industry.
Shaheen Chohan (08:31):
Now specific to the Middle East, has there been any physical damage to any of the regional large petrochemical assets that are operating there at the moment? Similar to what you may have seen in the refining sector.
Trey Hamblet (08:43):
Yes, there have, but not the same scale. There have been, I don't know, 12 to 18 industrial chemical assets; petrochemical plants have had some physical damage. A good number of those have done, you know, tidy, quick repairs and have come back online to some extent. Few remain still operational obviously. And you get deep into Iran and those we've got a lot of plants that are just completely offline.
When we look at the disruption to offline events, you know, downtime, your question, comparing it to refining. In refining we've seen, I think in the upwards of 500 plus offline events just in the Middle East, specific to the conflict that started in February, where there's been just north of 100 or so in the chemical industry. So it's definitely had its impact, but not the same impact.
Shaheen Chohan (09:36):
Trey, blue and green commodities. In past years, it's accounted for a fairly sizable proportion of the active project spending that you and your teams are tracking around the world. Now, obviously, we're seeing potentially a lot more pressure on the green side of the supply chain as opposed to the blue side. Are you actually seeing from the numbers that you are tracking a decoupling between those two parts of the supply chain?
Trey Hamblet (10:00):
I would say very much so. Yes, we're seeing evidence of that. And it's different depending on what part of the world you're in, what region of the world.
When we talk about that decoupling here in the US, it's a very significant difference because the incentives that were available have changed. The hurdles have changed. The commodity that feeds the feedstocks for these have changed, right? So on the blue side, it's very much a traditional technology. Traditional hydrogen units consuming natural gas, consuming ammonia units, consuming natural gas. So there's a very traditional process flow. Where on the green side, it's not traditional. We're dependent on renewable power. Renewable power is in high demand for data centers and so many other things going on in the US right now. So in green commodities we're already more expensive because you had to source renewable power, well now you got, you know, sourcing problems for that power.
And then you've got the other end of the problem with the green commodities, and that it has to go into an ecosystem that was designed for it to store it, to transport it, consume it, etc. So there's a lot of challenges, and those challenges differ as you move around the world.
Latin America was overly optimistic, as was Oceania, in my opinion, for planned and proposed capacity. That was just not anywhere near reasonable. So we're starting to see that pull back to something that we will find out. You know how much of it actually survives?
In Europe, green hydrogen is a very big part of their future, right? There's from memory, maybe 100, 140 billion dollars worth of green hydrogen planned proposed. I think we have maybe only 10 billion of that, ranked with a high probability, right? But Europe has been proactive and has amongst the largest operational fleet. We have less than 200 green hydrogen units in operation around the world today. And we've been talking about green hydrogen for a decade. It's no longer a new conversation.
We've got fewer than a dozen here in the US. Europe, I think, is approaching 80, maybe even closer to 100 over the next 12 months or so, followed by Asia, because there's been a significant movement of that. And there is a small mix of some blue commodities in Europe. There are some CO2 capture projects planned and proposed in Europe. They're minimal in comparison. There are still some plastic recycling investments planned and proposed across Europe, where that's diminished in other parts of the world.
So yes, there's been a divergence, a split between green and blue, and it really has its own life and the circumstances as you move to the different regions of the world.
Shaheen Chohan (12:52):
So if we look specifically at the US, which I guess was a market at the forefront of clean hydrogen and all things clean, there are still supportive tax incentives, I guess, more for the blue side of the supply chain as opposed to the green. So tax incentives in the US are still playing a big picture in influencing project spending. Do you still believe that green will be under pressure in blue? Maybe the actual, side of the supply chain that will actually show more momentum?
Trey Hamblet (13:22):
Yes. I would say that the blue is certainly going to be something that carries forward with in a simpler fashion, if you will, because of those tax incentives.
But, you know, the incentive dollars are complex because there's really strict timelines in which they have to be in development, in construction, online. There are some significant hurdles, so we've seen some of the largest blue projects that looked very, very promising, even while some of the biggest players, Exxon and others, are building significant pipelines to get the CO2 to underground storage and spending billions in underground storage; that's only going to be a fraction of what we saw, planned and proposed, but we will see it come to fruition.
On the green side, it's interesting, as much as we've seen and we've heard of discussions and talks about green hydrogen. On a global scale, there’s a couple hundred, less than 200 I think it is, operational green hydrogen at this point, still less than a dozen here in the United States in our backyard. The most significant portion of those are in Europe.
When we talk about Europe, the European green hydrogen is a significant part of their future. There's roughly, I think, a thousand projects or something being planned and proposed for green hydrogen in Europe. Of those, probably only about 200 or less, or what we would consider a high probability of taking place. So there's a significant shift in where we will actually see the green hydrogen versus the blue hydrogen or blue commodities.
Shaheen Chohan (14:52):
Now, sticking with Europe, historically it’s been a big chemical producing center but has really struggled, I guess, or been under stress over the last few years from two other epicenters: the Middle East and the US. Those two particular producing centers have always enjoyed, much more favorable cost-of-production advantage, right? And that's due to ample feedstock supply.
Now, with elevated naphtha prices, I can only assume that European producers already in operation are finding it even more difficult.
Is that altering the picture of European chemical projects spending away, possibly from those big, you know, basic petrochemical plants and production volumes, and more towards the clean side of the chemical slate?
As you said, Europe is a big green hydrogen market. Do you think under current conditions, we may see some project slippage due to the still high cost of feedstock?
Trey Hamblet (16:04):
Yes. I mean, we've continued to witness some fairly sizable chemical plants, traditional naphtha fed commodity plants closed. We know there are plans, you know, of additional closures, consolidations of the industry, and its traditional format. The green ESG motivated spending is at the top of the list. When you look at the biggest and the most robust projects planned for Europe, it's at a point where there's actually a very small percentage of those moving forward as a percentage of the whole. But when we look at the momentum overall, we look at their Fit for 55 and other initiatives; there's a lot of positive movement for those, probably more so in that region than most.
And our tools and analytic tools that we use internally show how some of these plans are shifting to the right, as we've talked about in our project fallout. And a lot of what's shifting are those green ESG initiative projects. We're not seeing them get canceled. They're just moving further out into the future and it's a big part of their future still.
Shaheen Chohan (17:10):
What's your level of confidence at this point in what's left for the remainder of 2026, or even what's been pushed into 2027? What's your top-line view?
Trey Hamblet (17:23):
Yeah, so it seems promising that we haven't retreated. We haven't fallen back any from where we saw our previous spend levels in 2025, which is promising to me.
You know, there's a multitude of geopolitical events, from Europe to the Middle East to Venezuela and Latin America. We've just got, you know, a lot coming at the industry. And so the fact that we're going to meet or exceed our spend level in 2025, I think is promising. And the fact that we're not seeing this huge increase in cancellations. We have seen a tick up to some degree in cancellations, and a lot of that is because of the green or blue projects that were just overly optimistic in the beginning. So we've seen that part of it tick up.
But when we look at traditional spend that hasn't, and when we look at, when I say traditional spend, here in the US, we've enjoyed, or we did enjoy for quite a long time a significant number of grassroot chemical plants, right? And the type of spend that we're going to see here and in some of the regions that's going to move more to expansions and additions with inside the fence and those don't, you know, cost to infrastructure and other things at the same levels. I feel optimistic that, you know, for the next year or two, we're going to be in pretty good shape.
Shaheen Chohan (18:45):
Now, specific to the US and Canada. Can we talk a little bit about the maintenance outlook? The US clearly must be capitalizing on some of this supply-demand sort of imbalance because we've locked out the Middle East in terms of trade flow. So this is a great window for US producers. And clearly they're running their units and their production rates at very high levels.
Have we seen planned maintenance for this year getting pushed out? So possibly we're going to have to take these units offline at some stage, right? They're working super hard. What do you see in terms of any adjustment to the pattern or the size or the timing of some of that planned maintenance?
Trey Hamblet (19:26):
Well, to your point a moment ago, I mean, the chemical fleet in the US has run hard and run long for quite a long period of time now. We've seen a year over year increase in the number of projects, the total spend for those projects continually increase over recent years, particularly since the restart, if you will, after the last Covid period. So from 21, 22 on forward, we don't see that slowing. Our numbers don't suggest that it will.
We've got some huge ethylene plants here in the United States. We could have 14, 15, maybe even 16 ethylene units come offline in 2027, and several of those will exceed 100, $150 million apiece. So there's some huge investments.
And then, you know, what's really interesting is, I've been in the industry long enough to remember when the phrase was coined, predictive and preventative maintenance. And then we started talking about big data. And we've arrived. We've arrived at the point in time where all that big data we collected, all that predictive and preventive maintenance, is being used in suites of AI and other tools to make, you know, hopefully smarter, better decisions. And that's actually driving up spending in many cases, right? Because we're taking those predictive models. We're taking the machine learning from from big data in past years and identifying weak points, soft points, and changing curves and lines. And that's equaling spending.
So I think that the advent of consuming the big data in this AI world is actually inflating maintenance in a positive mean. I don't mean inflating it unnecessarily; I mean it's inflating it to areas that increase efficiency, decrease downtimes, failures, things of that nature. So I think the maintenance outlook is positive.
Shaheen Chohan (21:20):
What are some of the key takeaways to remember as we navigate through the latter part of this year and then start to begin preparing our budgets and plans for the early start of 2027?
Trey Hamblet (21:34):
Sure. You know, there's probably 4 or 5 key things that would quickly come to my mind, and it's the ESG spend is going to continue to play a role despite the objections for it and some markets, despite the lack of incentives in some markets, despite the access to renewable power, it will continue to be something that's, you know, forefront in most discussions and conversations because as a global community, producers and consumers alike want that green flag, you know, for everything from their portfolio to their consumer wrapping. So ESG is going to continue to be a part of the conversation in some manner. In North America, particularly, we're going to remain very cost-advantaged. When you look at the price of energy and commodity feedstocks. So North America has a very cost-advantaged region that is going to be something that helps, I think, build an opportunity for more spending in 27, 28, and in later years.
The chemical industry is very consumer-centric, and it doesn't matter which of the large oil and gas companies and other developers you listen to; they talk about population growth, and population growth is just continuing. It is not slowing. And so that's going to continue to be a positive element for the chemical industry because it has population growth. It just comes back to chemical demand quite simply. On the constraint side of it, you know, the geopolitical scene just continues to drag on and on. And the length of time it takes us to get to where we feel there's some stability, that we want to make a long-term decision. We have a good appreciation for trade flow changes. We have a good appreciation for, how is it going to influence demand or recovery investments to rebuild assets? You know, that's going to be one of those constraints that only time is going to tell us the answer to.
Kind of thinking back to that ESG comment one more time. The flip side of the ESG comment is that those technologies are very expensive, right? And they are competing with that cost advantage we have in North America. So when you think about Europe, and you think about the $140 billion they currently have planned with some green or blue flag in it, we're probably on again about, you know, 10, 15% of it because of the nature of what it costs in comparison to cost advantages in other parts of the world.
Shaheen Chohan (24:02):
That brings us to the end of our discussion. I guess it is fair to say that the outlook right now looks like one of cautious optimism, with projects spending being, I guess, reallocated on a more tactical basis towards those higher value specialty chemicals rather than, as we've seen in the past, on the big building block petrochemical expansions.
So all that leaves me to do now is just say a very big thanks to you, Trey, for sharing your insights and perspectives. Very much enjoyed the discussion. If any of you who have joined us have any further questions about any of the points that we've discussed today, then please do reach out to myself or Trey via our contact details that you can see here.
And finally, of course, a very big thanks to all of you who have taken time out to join us. I hope we have helped you all better navigate some of the currents of change that we are seeing. Welcome to the Answer Age.
Global chemical production growth has softened over much of the course of this year, some of which is due to still moderate only economic activity and softer demand across some of those key end-use markets. And all of this is coming at a time when overcapacity remains a core problem right now. So the big questions remain: how will capital spending play out over the course of this year and into next off rising feedstock costs for many producers? And will the green and blue commodities that have been a growth engine for the last year continue, or will they falter?
Welcome to Navigating the Currents of Change, where we bring together over four decades of trusted research, data, and industry insights, built for the Answer Age. Let's dive in. My name is Shaheen Chohan, and I lead Global Analytics here at Industrial Info Resources.
And to help me unpick some of the trends and put some answers to those questions, I am delighted to be joined by Trey Hamblet, who is IIR's Senior Vice President of Chemical Processing Research. Welcome, Trey.
Trey Hamblet (01:26):
Thanks for having me.
Shaheen Chohan (01:26):
Now, Trey, your industry obviously aligns very closely to the ebbs and flows of the broader economic performance. Has the chemical industry and the levels of spending that we've seen in previous years, is it still moving at pace and proceeding? Certainly of the first half of this year, or have we seen some erosion of that planned spending?
Trey Hamblet (01:46):
So we've seen a little bit of both. You know, in some respects, when we look at where the spend levels were in 2025 at the same time, and we're kind of on par, we're kind of keeping pace.
We've had an anomaly, I'll call it, really, for the last five plus years in this huge accumulation of projects and pent-up spending we've started each year with. We reached a new historical high when we got to the beginning of 2026. We had just short of $1 trillion globally across the chemical industry that had some potential to start construction this year.
As always happens, we see those plans move. Roughly 85% of that fallout stayed and in some phase of active planning. So that's a good thing. Meaning that there's expectations and optimism that we're going to continue to see those projects move. Much of it moved into 27. Some of it moved out as far as 2030 or 2031.
So we started the year somewhat in a similar fashion than we have in the past, and that we were seeing this accumulation of projects continue to move forward. We've seen a slight uptick in cancellations in some regions more than others.
You may have mentioned in your question about blue and green, and certainly here in the domestic market where I reside in the US, we've seen an increase in the cancellation of green hydrogen, blue, you know, carbon capture projects, etc., but that's kind of where we start for the year.
Shaheen Chohan (03:23):
Now, gone are the days of the multiple big ethylene capacity waves that we've seen over the last decade in the US. What we are seeing is most of the new capacity that is being built, and certainly still being proposed, seems to be in Asia and more specifically in China. Why is that?
Trey Hamblet (03:41):
Well, you know, Asia is the epicenter of demand, right? We hear about population growth. It's one of the key components that drives chemical industry spending is population growth. Because with population growth you have more plastics. You have more paints, coatings, automobiles. Everything that we consume has a plastic or chemical component to it, right? And Asia is one of those biggest growth markets.
What's interesting talking about China specifically is China produces a great deal of ethylene, one of the father chemicals of the chemical industry, if you will, because it's, you know, the starting point for some of the other commodities in the industry.
There's some 60 plus billion dollars worth of future, you know, years not this year, not next year, but future years worth of investments for ethylene alone.
What's interesting is we've got 60 plus billion in green hydrogen in China as well. And that's a relatively new phenomenon. And green hydrogen probably makes more sense in some respects for that region than others, because there's some 8000 renewable power projects planned across China, right? So their access to that renewable power, even if we only saw a fraction of that come to fruition, you know, would be very supportive of that green hydrogen.
So you've got traditional investments, ethylene, you've got the newer green hydrogen, which might turn into green ammonia and other commodities. So China is going to continue to be that, you know, epicenter of growth going forward as it has played that leading role in the last decade or more.
Shaheen Chohan (05:13):
Looking at the macro picture, chemicals haven't so far been on the radar for US tariffs so far. But obviously geopolitics does play a more, I guess, indirect role in influencing some of those chemical project investments and the considerations and decisions, just simply by the very global nature of production and also trade flow. Have you seen any major disruptions to the sort of balance between supply and demand, and how has that shifted the location or indeed the type of projects that are still being proposed?
Trey Hamblet (05:57):
Yes. So we've seen the geopolitical and other, you know, conflicts we've experienced this year have a significant impact on trade flows. You mentioned trade flows in your question. And when we used our Energy Capacity Insights tool, where we look at future capacities, we look at operational base of capacities, future offline events, etc., we saw a significant drop in operating rates specifically for ethylene. Again, one of those commodities that's, you know, a starting point for so much else in the industry.
When the year started, we had on average, a four, maybe 5% offline capacity globally for ethylene when you rolled into March and April, when we got into our deepest trenches of the geopolitical escalations this year, we saw as much as 17% of that capacity offline globally, which is tremendous. That's an equivalent of, I think, 66 or so billion pounds equivalent of ethylene capacity offline at once.
It wasn't just in the Middle East, and it wasn't just in the Russia-Ukraine environment. This was in Japan, Korea, China. When the trade flows for naphtha, which is a key feedstock for ethylene in those Asian and European regions, stopped or got disrupted, it had a significant impact on operating rates and trade flows.
And of course, this is influencing decisions on future maintenance plants because we don't know yet for some of these producers in China, Japan or Korea, just using some easy examples that had unplanned time for 30 days, 60 days going on 90 days in some cases of derails or completely offline, we don't know yet. Did they take an optimistic view and perform some maintenance that had been originally planned for 27 or 28? And so now that turnarounds move forward, or did they use that to say, okay, we're going to take that window and go even longer before the next turnaround because we didn't run during this period? So that's going to have an impact on maintenance decisions and we'll start to reveal that or interpret what that means to the market over the coming months.
But it also puts stress on decisions for capital projects. Right? The indecision and operating rates and storage volumes and trade flows makes it really difficult to make a decision on some of your really large CapEx projects that are benchmarks in the industry.
Shaheen Chohan (08:31):
Now specific to the Middle East, has there been any physical damage to any of the regional large petrochemical assets that are operating there at the moment? Similar to what you may have seen in the refining sector.
Trey Hamblet (08:43):
Yes, there have, but not the same scale. There have been, I don't know, 12 to 18 industrial chemical assets; petrochemical plants have had some physical damage. A good number of those have done, you know, tidy, quick repairs and have come back online to some extent. Few remain still operational obviously. And you get deep into Iran and those we've got a lot of plants that are just completely offline.
When we look at the disruption to offline events, you know, downtime, your question, comparing it to refining. In refining we've seen, I think in the upwards of 500 plus offline events just in the Middle East, specific to the conflict that started in February, where there's been just north of 100 or so in the chemical industry. So it's definitely had its impact, but not the same impact.
Shaheen Chohan (09:36):
Trey, blue and green commodities. In past years, it's accounted for a fairly sizable proportion of the active project spending that you and your teams are tracking around the world. Now, obviously, we're seeing potentially a lot more pressure on the green side of the supply chain as opposed to the blue side. Are you actually seeing from the numbers that you are tracking a decoupling between those two parts of the supply chain?
Trey Hamblet (10:00):
I would say very much so. Yes, we're seeing evidence of that. And it's different depending on what part of the world you're in, what region of the world.
When we talk about that decoupling here in the US, it's a very significant difference because the incentives that were available have changed. The hurdles have changed. The commodity that feeds the feedstocks for these have changed, right? So on the blue side, it's very much a traditional technology. Traditional hydrogen units consuming natural gas, consuming ammonia units, consuming natural gas. So there's a very traditional process flow. Where on the green side, it's not traditional. We're dependent on renewable power. Renewable power is in high demand for data centers and so many other things going on in the US right now. So in green commodities we're already more expensive because you had to source renewable power, well now you got, you know, sourcing problems for that power.
And then you've got the other end of the problem with the green commodities, and that it has to go into an ecosystem that was designed for it to store it, to transport it, consume it, etc. So there's a lot of challenges, and those challenges differ as you move around the world.
Latin America was overly optimistic, as was Oceania, in my opinion, for planned and proposed capacity. That was just not anywhere near reasonable. So we're starting to see that pull back to something that we will find out. You know how much of it actually survives?
In Europe, green hydrogen is a very big part of their future, right? There's from memory, maybe 100, 140 billion dollars worth of green hydrogen planned proposed. I think we have maybe only 10 billion of that, ranked with a high probability, right? But Europe has been proactive and has amongst the largest operational fleet. We have less than 200 green hydrogen units in operation around the world today. And we've been talking about green hydrogen for a decade. It's no longer a new conversation.
We've got fewer than a dozen here in the US. Europe, I think, is approaching 80, maybe even closer to 100 over the next 12 months or so, followed by Asia, because there's been a significant movement of that. And there is a small mix of some blue commodities in Europe. There are some CO2 capture projects planned and proposed in Europe. They're minimal in comparison. There are still some plastic recycling investments planned and proposed across Europe, where that's diminished in other parts of the world.
So yes, there's been a divergence, a split between green and blue, and it really has its own life and the circumstances as you move to the different regions of the world.
Shaheen Chohan (12:52):
So if we look specifically at the US, which I guess was a market at the forefront of clean hydrogen and all things clean, there are still supportive tax incentives, I guess, more for the blue side of the supply chain as opposed to the green. So tax incentives in the US are still playing a big picture in influencing project spending. Do you still believe that green will be under pressure in blue? Maybe the actual, side of the supply chain that will actually show more momentum?
Trey Hamblet (13:22):
Yes. I would say that the blue is certainly going to be something that carries forward with in a simpler fashion, if you will, because of those tax incentives.
But, you know, the incentive dollars are complex because there's really strict timelines in which they have to be in development, in construction, online. There are some significant hurdles, so we've seen some of the largest blue projects that looked very, very promising, even while some of the biggest players, Exxon and others, are building significant pipelines to get the CO2 to underground storage and spending billions in underground storage; that's only going to be a fraction of what we saw, planned and proposed, but we will see it come to fruition.
On the green side, it's interesting, as much as we've seen and we've heard of discussions and talks about green hydrogen. On a global scale, there’s a couple hundred, less than 200 I think it is, operational green hydrogen at this point, still less than a dozen here in the United States in our backyard. The most significant portion of those are in Europe.
When we talk about Europe, the European green hydrogen is a significant part of their future. There's roughly, I think, a thousand projects or something being planned and proposed for green hydrogen in Europe. Of those, probably only about 200 or less, or what we would consider a high probability of taking place. So there's a significant shift in where we will actually see the green hydrogen versus the blue hydrogen or blue commodities.
Shaheen Chohan (14:52):
Now, sticking with Europe, historically it’s been a big chemical producing center but has really struggled, I guess, or been under stress over the last few years from two other epicenters: the Middle East and the US. Those two particular producing centers have always enjoyed, much more favorable cost-of-production advantage, right? And that's due to ample feedstock supply.
Now, with elevated naphtha prices, I can only assume that European producers already in operation are finding it even more difficult.
Is that altering the picture of European chemical projects spending away, possibly from those big, you know, basic petrochemical plants and production volumes, and more towards the clean side of the chemical slate?
As you said, Europe is a big green hydrogen market. Do you think under current conditions, we may see some project slippage due to the still high cost of feedstock?
Trey Hamblet (16:04):
Yes. I mean, we've continued to witness some fairly sizable chemical plants, traditional naphtha fed commodity plants closed. We know there are plans, you know, of additional closures, consolidations of the industry, and its traditional format. The green ESG motivated spending is at the top of the list. When you look at the biggest and the most robust projects planned for Europe, it's at a point where there's actually a very small percentage of those moving forward as a percentage of the whole. But when we look at the momentum overall, we look at their Fit for 55 and other initiatives; there's a lot of positive movement for those, probably more so in that region than most.
And our tools and analytic tools that we use internally show how some of these plans are shifting to the right, as we've talked about in our project fallout. And a lot of what's shifting are those green ESG initiative projects. We're not seeing them get canceled. They're just moving further out into the future and it's a big part of their future still.
Shaheen Chohan (17:10):
What's your level of confidence at this point in what's left for the remainder of 2026, or even what's been pushed into 2027? What's your top-line view?
Trey Hamblet (17:23):
Yeah, so it seems promising that we haven't retreated. We haven't fallen back any from where we saw our previous spend levels in 2025, which is promising to me.
You know, there's a multitude of geopolitical events, from Europe to the Middle East to Venezuela and Latin America. We've just got, you know, a lot coming at the industry. And so the fact that we're going to meet or exceed our spend level in 2025, I think is promising. And the fact that we're not seeing this huge increase in cancellations. We have seen a tick up to some degree in cancellations, and a lot of that is because of the green or blue projects that were just overly optimistic in the beginning. So we've seen that part of it tick up.
But when we look at traditional spend that hasn't, and when we look at, when I say traditional spend, here in the US, we've enjoyed, or we did enjoy for quite a long time a significant number of grassroot chemical plants, right? And the type of spend that we're going to see here and in some of the regions that's going to move more to expansions and additions with inside the fence and those don't, you know, cost to infrastructure and other things at the same levels. I feel optimistic that, you know, for the next year or two, we're going to be in pretty good shape.
Shaheen Chohan (18:45):
Now, specific to the US and Canada. Can we talk a little bit about the maintenance outlook? The US clearly must be capitalizing on some of this supply-demand sort of imbalance because we've locked out the Middle East in terms of trade flow. So this is a great window for US producers. And clearly they're running their units and their production rates at very high levels.
Have we seen planned maintenance for this year getting pushed out? So possibly we're going to have to take these units offline at some stage, right? They're working super hard. What do you see in terms of any adjustment to the pattern or the size or the timing of some of that planned maintenance?
Trey Hamblet (19:26):
Well, to your point a moment ago, I mean, the chemical fleet in the US has run hard and run long for quite a long period of time now. We've seen a year over year increase in the number of projects, the total spend for those projects continually increase over recent years, particularly since the restart, if you will, after the last Covid period. So from 21, 22 on forward, we don't see that slowing. Our numbers don't suggest that it will.
We've got some huge ethylene plants here in the United States. We could have 14, 15, maybe even 16 ethylene units come offline in 2027, and several of those will exceed 100, $150 million apiece. So there's some huge investments.
And then, you know, what's really interesting is, I've been in the industry long enough to remember when the phrase was coined, predictive and preventative maintenance. And then we started talking about big data. And we've arrived. We've arrived at the point in time where all that big data we collected, all that predictive and preventive maintenance, is being used in suites of AI and other tools to make, you know, hopefully smarter, better decisions. And that's actually driving up spending in many cases, right? Because we're taking those predictive models. We're taking the machine learning from from big data in past years and identifying weak points, soft points, and changing curves and lines. And that's equaling spending.
So I think that the advent of consuming the big data in this AI world is actually inflating maintenance in a positive mean. I don't mean inflating it unnecessarily; I mean it's inflating it to areas that increase efficiency, decrease downtimes, failures, things of that nature. So I think the maintenance outlook is positive.
Shaheen Chohan (21:20):
What are some of the key takeaways to remember as we navigate through the latter part of this year and then start to begin preparing our budgets and plans for the early start of 2027?
Trey Hamblet (21:34):
Sure. You know, there's probably 4 or 5 key things that would quickly come to my mind, and it's the ESG spend is going to continue to play a role despite the objections for it and some markets, despite the lack of incentives in some markets, despite the access to renewable power, it will continue to be something that's, you know, forefront in most discussions and conversations because as a global community, producers and consumers alike want that green flag, you know, for everything from their portfolio to their consumer wrapping. So ESG is going to continue to be a part of the conversation in some manner. In North America, particularly, we're going to remain very cost-advantaged. When you look at the price of energy and commodity feedstocks. So North America has a very cost-advantaged region that is going to be something that helps, I think, build an opportunity for more spending in 27, 28, and in later years.
The chemical industry is very consumer-centric, and it doesn't matter which of the large oil and gas companies and other developers you listen to; they talk about population growth, and population growth is just continuing. It is not slowing. And so that's going to continue to be a positive element for the chemical industry because it has population growth. It just comes back to chemical demand quite simply. On the constraint side of it, you know, the geopolitical scene just continues to drag on and on. And the length of time it takes us to get to where we feel there's some stability, that we want to make a long-term decision. We have a good appreciation for trade flow changes. We have a good appreciation for, how is it going to influence demand or recovery investments to rebuild assets? You know, that's going to be one of those constraints that only time is going to tell us the answer to.
Kind of thinking back to that ESG comment one more time. The flip side of the ESG comment is that those technologies are very expensive, right? And they are competing with that cost advantage we have in North America. So when you think about Europe, and you think about the $140 billion they currently have planned with some green or blue flag in it, we're probably on again about, you know, 10, 15% of it because of the nature of what it costs in comparison to cost advantages in other parts of the world.
Shaheen Chohan (24:02):
That brings us to the end of our discussion. I guess it is fair to say that the outlook right now looks like one of cautious optimism, with projects spending being, I guess, reallocated on a more tactical basis towards those higher value specialty chemicals rather than, as we've seen in the past, on the big building block petrochemical expansions.
So all that leaves me to do now is just say a very big thanks to you, Trey, for sharing your insights and perspectives. Very much enjoyed the discussion. If any of you who have joined us have any further questions about any of the points that we've discussed today, then please do reach out to myself or Trey via our contact details that you can see here.
And finally, of course, a very big thanks to all of you who have taken time out to join us. I hope we have helped you all better navigate some of the currents of change that we are seeing. Welcome to the Answer Age.
Please Select A Language
*This episode is brought to you by Industrial Info's Latin American Office in Argentina.