Metals & Minerals
Mining Some Signs of Life in Global Metals & Minerals Industry
A multiyear demand growth cycle for the Metals & Minerals Industry, which saw project spending for mining and steel projects accumulate, peaked in 2008.
Released Thursday, April 16, 2009
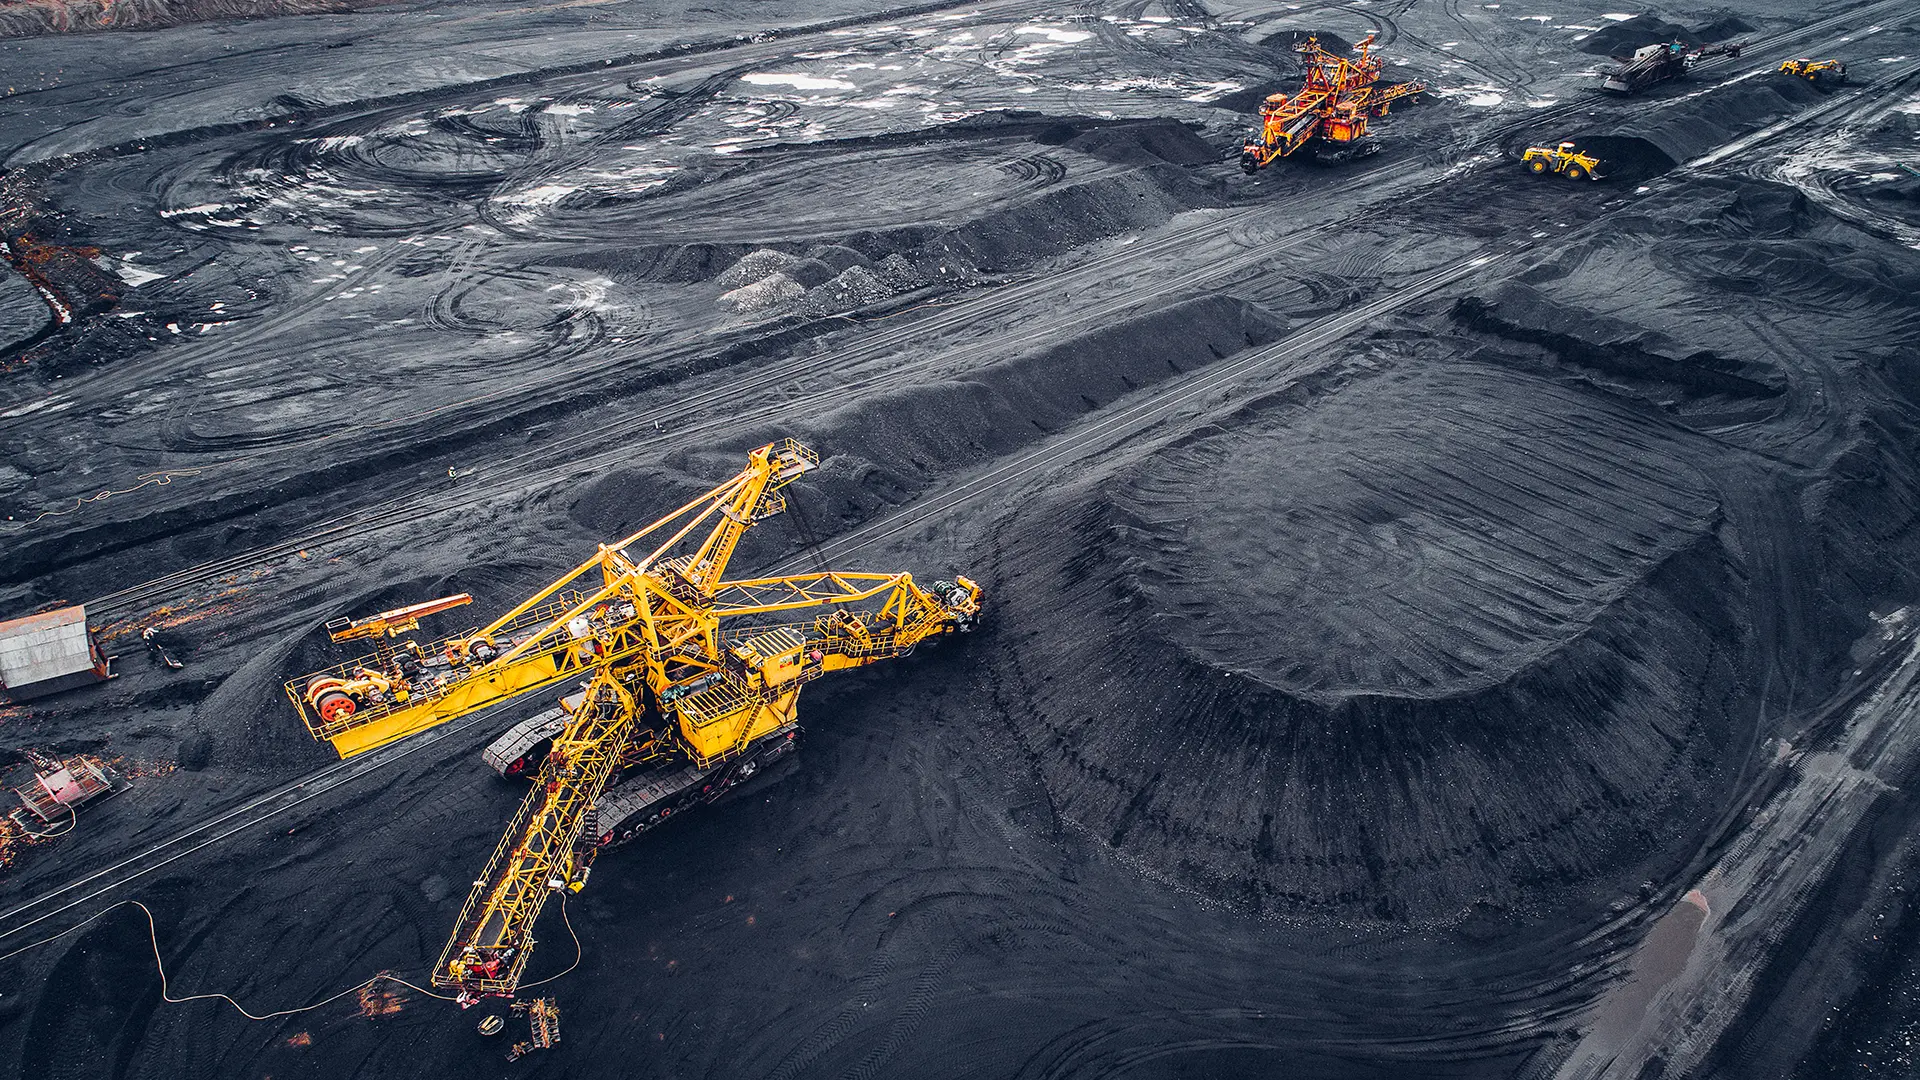
Researched by Industrial Info Resources (Sugar Land, Texas)--A multiyear demand growth cycle for the Metals & Minerals Industry, which saw project spending for mining and steel projects accumulate, peaked in 2008. Project costs accelerated too, and then demand evaporated during the second half of 2008, culminating in extraordinary pullback in project development. Steel mills are currently operating at 50% capacity. Projects were stopped cold in mid-construction or have been extended over longer periods of time to spread out the costs. Many other projects have been delayed.
Many of the projects developed over the last five years are under construction and continue to move forward, keeping an army of engineering and construction contractors busy. There is currently more than $30 billion worth of Metals & Minerals Industry projects under construction in North America alone. The momentum from this will continue for the next two to three years. However, recent economic regression, weakening commodity prices, credit/lending tightening and rising project costs are major constraints putting downward pressure on the industry in 2009. This being said, certain commodities are experiencing increased demand even during the current economic slowdown, resulting in project development. Also, energy costs are at historic lows. Crude oil has dropped from $147 per barrel last summer to about $50 per barrel at the moment. Natural gas costs have dropped from $14 to $3.5 per million BTUs. This could reduce project development costs by as much as 20% and should help bolster project activity globally.
Metals & Minerals Industry firms continue to monitor the market closely in 2009. Most firms have reduced production and capital expenditures where necessary. However, a few have increased capital spending, such as Chilean copper giant Codelco. If the downturn is prolonged it will cut into company profits leading to more reductions. This can do nothing but have a negative impact on the equipment and service providers that earn their livelihood from serving these companies. However, because of increased activity in recent years, most of the equipment and service providers have a significant backlog of orders, which will help to defer the impact of the economic recession at least in the near term.
Recently, there have been some promising indicators that the market is turning around, supported by the much publicized U.S. and G20 stimulus incentives. In March 2009, some commodity prices have ended free fall status and appear to have reached the bottom of the cycle. Whether this a temporary blip or an extended bull market has yet to be seen.
Prior to the current economic recession, project backlogs and extended delivery periods for fabricated long-lead equipment items were commonplace for booming industries such as ethanol, refining, pipelines and mining, and prices for project development skyrocketed as a result. Resources of engineering expertise, labor and equipment became scarce at the same time, placing additional constraints on projects and further driving up project costs. Equipment and service providers have been the busiest they've been in years during this time and have experienced record profits and growth.
With the recent economic downturn, demand for items such as steel, metals and other manufacturing goods has declined worldwide. Many projects have been delayed with a few cancellations. However, there are certain markets where projects continue to move forward. Lithium, polysilicon, coal and gold projects are moving forward in this economy, and global project development for these commodities is on the rise.
Chinese steel makers are taking advantage of favorable prices to acquire stakes in major Australian iron ore mining and shipping projects, moving billion-dollar mining projects forward. This period has also experienced an increase in merger and acquisition activity.
It is more important than ever for equipment and service providers to be aware of market moves and keep track of project developments. Already a highly competitive market, equipment and service providers will have to adapt to market swings by offering new products and services, targeting new sectors sometimes out of their comfort zones or areas of expertise.
Historically, the mining sector makes up about 50% of the total spending in the Metals & Minerals Industry. Mining sectors receiving most of the development dollars these days are coal, oil sands, potash, copper, gold, iron ore, lithium and uranium, mainly because of rising demand and commodity prices. The main concerns of the mining industry today are financing, energy costs, mine safety, environmental/regulatory/permitting issues, workforce availability, availability of construction materials, long-lead equipment deliveries and cost escalations. These are all major considerations and constraints to mine-project development.
Industrial Info Resources (IIR) is a marketing information service specializing in industrial process, energy and financial related markets with products and services ranging from industry news, analytics, forecasting, plant and project databases, as well as multimedia services.
/news/article.jsp
false
Want More IIR News Intelligence?
Make us a Preferred Source on Google to see more of us when you search.
Add Us On GoogleAsk Us
Have a question for our staff?
Submit a question and one of our experts will be happy to assist you.
Forecasts & Analytical Solutions
Where global project and asset data meets advanced analytics for smarter market sizing and forecasting.
Explore Our SolutionsRelated Articles
-
ABB Builds Backlog with Canadian Mining, U.S. Tech WorkOctober 21, 2026
-
Antofagasta Minerals Boosts Copper OutputOctober 21, 2026
PECWeb Global Market Intelligence Platform
Identify opportunities, anticipate change, and execute with confidence. PECWeb connects the industrial intelligence you need, from projects and assets to operational events, all in one platform.
Discover PecwebIndustry Intel
-
Brazil Critical Minerals 2027: Rare Earths, Lithium, CopperPodcast Episode / Oct 16, 2026
-
US Craft Labor Outlook 2026: Wages, Per Diems, Data CentersPodcast Episode / Oct 16, 2026
-
Latin America Data Center Outlook 2026: Power, Hubs & GrowthPodcast Episode / Oct 9, 2026
-
Food and Beverage CapEx Outlook 2026: Tariffs, AI, AfricaPodcast Episode / Oct 9, 2026
-
North America Refining 2026: New Pipelines to PADD 5Podcast Episode / Oct 2, 2026